Budgeting Tips to Manage Short-Term Loan Repayment
Practical budgeting tips to manage short-term loan repayment: build a simple budget, set aside funds early, and cut flexible expenses to avoid late fees.
By Brianna Washington
When you take out a short-term loan, the repayment date can arrive faster than expected. Whether you used a payday loan, cash advance, or personal loan to cover an urgent expense, the key to avoiding rollover fees and mounting debt is a solid budgeting plan. Without one, it is easy to fall behind, triggering late fees and damaging your credit score. The good news is that you do not need a finance degree to stay on top of your loan. By following a few practical budgeting tips, you can manage your short-term loan repayment responsibly and protect your financial health.
Build a Simple Monthly Budget That Includes Your Loan Payment
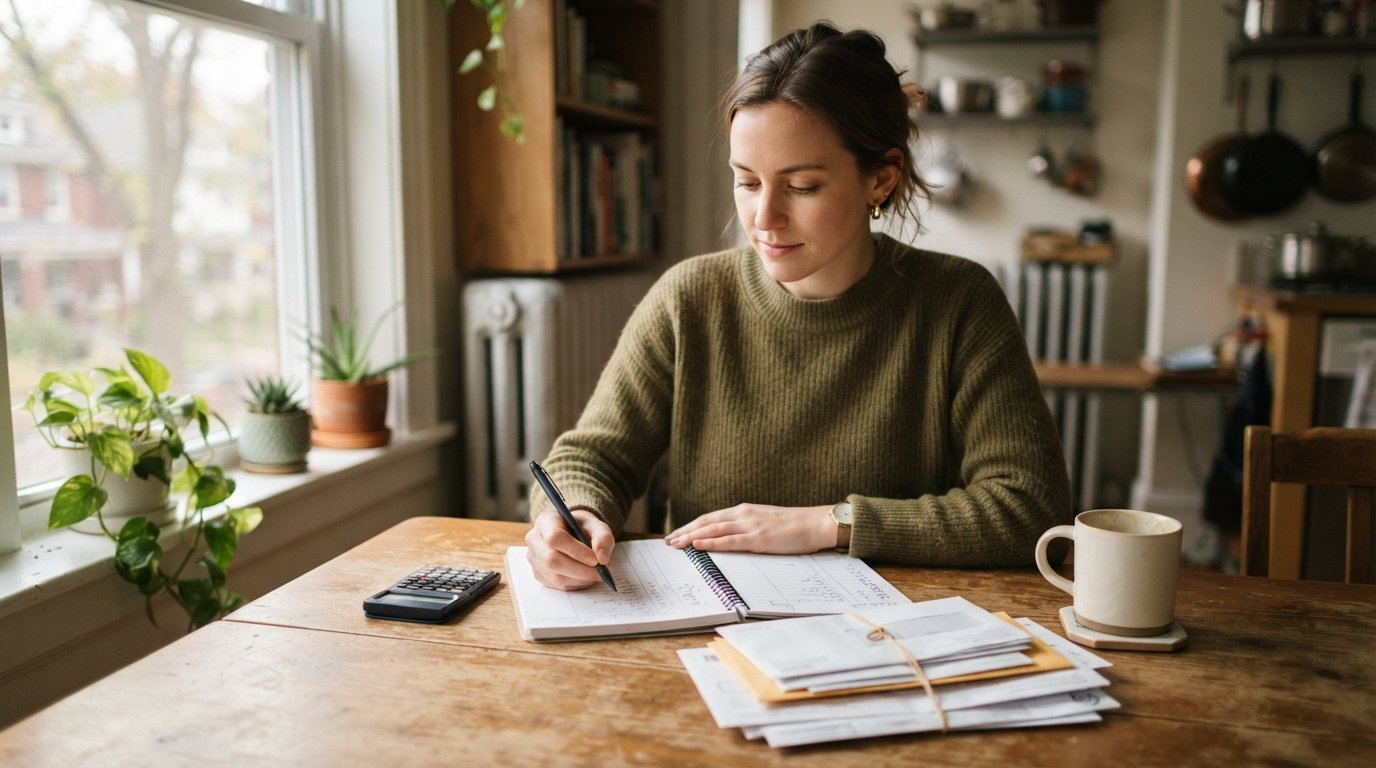
The foundation of any successful repayment strategy is a clear, realistic budget. Many borrowers focus only on the loan payment and forget to account for everyday expenses, which leads to shortfalls. To avoid this, start by listing all your income sources for the month, including your salary, side gigs, and any other regular cash inflows. Then, list every expense: rent or mortgage, utilities, groceries, transportation, insurance, and debt payments. The goal is to see exactly how much money is left after essential costs.
Next, slot your short-term loan payment into the budget as a fixed expense. Treat it with the same priority as your rent or utilities. If your loan requires a lump-sum repayment, divide that amount by the number of paychecks you will receive before the due date and set aside that portion each payday. For example, if you owe $300 and get paid twice before the due date, you need to reserve $150 from each paycheck.
To make budgeting easier, consider using a simple spreadsheet or a budgeting app. Many free tools let you categorize expenses and track your progress. The key is to be honest about your spending and to review your budget regularly. A budget is not a one-time exercise; it should evolve as your income and expenses change.
If you are new to budgeting, start with the 50/30/20 rule: 50% of your income for needs, 30% for wants, and 20% for savings and debt repayment. While this may not fit every situation, it provides a helpful starting point. Adjust the percentages based on your loan payment size and other obligations. For more guidance on responsible borrowing, see our article on smart strategies for responsible short-term borrowing.
Set Aside Funds Before the Due Date
One of the most effective ways to ensure on-time repayment is to set aside money as soon as you receive it. Waiting until the due date to scramble for cash often leads to missed payments or expensive rollovers. Instead, create a dedicated savings account or a separate envelope for your loan repayment. As soon as you get paid, transfer the allocated amount immediately. This removes the temptation to spend it on non-essential items.
Automating the process can be even more effective. Set up an automatic transfer from your checking account to your savings account on each payday. If your lender allows automatic payments, you can also schedule those, but be sure you have enough in your account to avoid overdraft fees. Automation helps you stay consistent and reduces the mental load of remembering due dates.
Another strategy is to use a calendar or reminder system. Mark the due date on your calendar and set alerts a week before and a few days before. This gives you a buffer to double-check that the funds are available. If you receive irregular income, such as from freelance work, set aside a larger portion during high-income months to cover lean periods.
Consider using the envelope system for cash expenses. Allocate cash for groceries, entertainment, and other variable spending, and keep the loan repayment money separate. This visual and physical separation can help you avoid accidentally spending money earmarked for your loan.
Cut Flexible Expenses to Protect Repayment
When money is tight, it is crucial to prioritize your loan repayment over discretionary spending. Review your budget and identify expenses that can be reduced or eliminated temporarily. Common flexible expenses include dining out, subscription services, entertainment, and non-essential shopping. By cutting back on these items, you free up cash to put toward your loan.
Start by tracking your spending for a week or two to see where your money goes. You might be surprised at how small purchases add up. For instance, a daily $5 coffee adds up to $150 a month. Redirecting that money to your loan payment can make a significant difference. Similarly, consider negotiating bills or switching to cheaper plans for utilities, phone, and insurance.
Here are some practical ways to cut flexible expenses without feeling deprived:
- Cancel unused subscriptions and memberships.
- Cook at home more often and pack lunches for work.
- Use public transportation or carpool to save on gas and parking.
- Entertainment: look for free community events or use streaming services instead of cable.
- Delay non-essential purchases until after the loan is repaid.
Remember, these cuts are temporary. Once the loan is repaid, you can gradually reintroduce some of these expenses. The goal is to create breathing room in your budget so that your loan payment is never at risk.
If you find that your income is insufficient to cover both essentials and your loan, you may need to explore additional income sources. A side gig, freelance work, or selling unused items can provide extra cash. However, be cautious about taking on more debt to repay existing debt, as this can lead to a cycle of borrowing.
Why On-Time Repayment Matters for Financial Health
Paying your short-term loan on time is about more than just avoiding late fees. It is a critical component of your overall financial health. Late payments can be reported to credit bureaus, which can lower your credit score and make it harder to obtain credit in the future. Even if your lender does not report to credit bureaus, missed payments can lead to aggressive collection tactics and legal action.
On-time repayment also helps you build a positive payment history, which is a key factor in your credit score. If you are using a short-term loan to bridge a gap, demonstrating responsible repayment can improve your creditworthiness over time. This can lead to better loan terms and lower interest rates in the future.
Furthermore, timely repayment reduces stress and financial anxiety. Knowing that you have a plan and are meeting your obligations provides peace of mind. It also helps you avoid the trap of rolling over the loan, which can significantly increase the cost of borrowing. Rollover fees and interest can quickly accumulate, turning a small loan into a large debt.
If you are struggling to make a payment, communicate with your lender immediately. Many lenders offer hardship plans or alternative payment arrangements. Ignoring the problem will only make it worse. Be proactive and seek help if needed.
For those who are considering a short-term loan, it is wise to connect with a reputable service that can match you with lenders. StartPaydayLoan is a free online connection service that helps U.S. consumers find short-term and payday loan options. Visitors complete one simple request form and may be matched with third-party lenders in our network. StartPaydayLoan is not a lender and does not make credit decisions; any loan terms come directly from the lender. Always review the terms carefully before accepting a loan.
Additional Budgeting Tips for Short-Term Loan Repayment
Beyond the core strategies, there are several other tactics that can help you stay on track. First, build an emergency fund, even if it is small. Having a cushion of $500 to $1,000 can prevent you from needing another loan when unexpected expenses arise. Start by saving a small amount each week.
Second, avoid taking on new debt while repaying your current loan. It is tempting to use credit cards or other loans to cover gaps, but this can lead to a debt spiral. If you must borrow, explore all options and understand the terms.
Third, consider making biweekly payments instead of monthly if your lender allows. This can reduce the total interest paid and make the payments more manageable. However, be sure to confirm with your lender that there are no prepayment penalties.
Finally, review your budget and repayment plan regularly. Life changes, and your budget should adapt. If you get a raise or a bonus, consider putting extra money toward your loan to pay it off faster. Conversely, if you face a financial setback, adjust your budget accordingly and communicate with your lender.
By following these budgeting tips, you can manage your short-term loan repayment effectively and move toward a more secure financial future. Remember, the key is to plan ahead, prioritize your loan payment, and make adjustments as needed.